

– by New Deal democrat
There’s no important new financial information immediately, so let’s take an up to date have a look at the downstream results on the availability chain and retail gross sales so removed from T—-p’s tariffs.
To start with, not less than a few of the tariffs are certainly in impact. Here’s a graph from Ben Casselman of The NY Occasions:
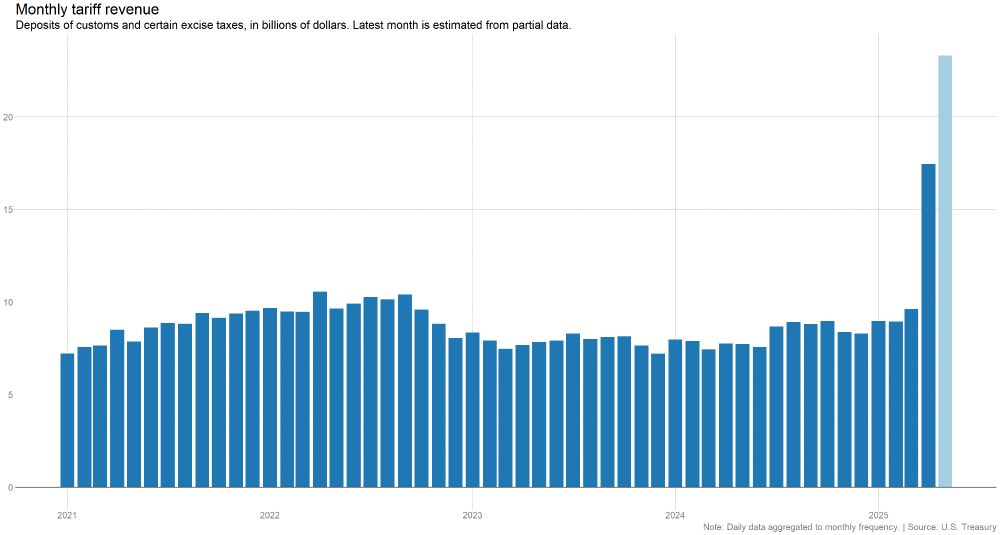
Not solely was there a pointy improve in April, however in Could to this point he experiences that the federal government is on observe to gather $23 Billion in tariffs, which he says is about 3x the revenues in contrast with Could final 12 months.
That income is popping out of company income and/or customers’ pockets, relying on how a lot firms are capable of go on vs. eat.
Let’s begin trying on the provide chain with this graph from Torsten Slok of Apollo Investments by way of Carl Quintanilla exhibiting trans-Pacific ships crusing from China to the US:

For the final three weeks, this transport has been at or very near 12 month lows, regardless of the “pause” within the commerce battle. As one wag mentioned, “it’s almost as if companies cannot make any near-term plans” as a result of the state of affairs may change at any second.
Downstream of which might be arrivals at US ports. The port of LA updates its inbound container rely each week, together with scheduled arrivals over the subsequent three weeks. Right here is its newest, by June 14:

For the reason that week of April 26, with one exception – that corresponds with the transient revival of trans-Pacific transport in early Could – each week has proven a lower from the corresponding week in 2024. Cumulatively to this point within the seven weeks since, scheduled arrivals have totaled 611,000 TEU’s, vs. 679,000 in 2024, a precise -10.0% decline.
As soon as containers arrive at US ports, the subsequent step is transport by way of rail (normally) or truck (usually for shorter hauls). Whereas I’m not conscious of any weekly or related information for truck volumes, the AAR does replace intermodal visitors each week. Right here is its YoY information for intermodal rail visitors by the week of Could 3:

Be aware that rail visitors usually bottoms at concerning the finish of March, and begins rising all the way in which in direction of the Vacation Season starting in April. Against this, this 12 months intermodal visitors continued to development downwards in April.
And though it isn’t proven within the graph above, within the two weeks since that development has continued. For the week of Could 10 there have been 273,000 intermodal containers, a YoY improve of 5.7%. For the week of Could 17 it was 262,000, a mere 0.3% improve YoY.
In Could and June of final 12 months, weekly rail intermodal hundreds averaged about 285,000. If we extrapolate from the -10% YoY decline in port visitors, that brings us all the way down to about 255,000 hundreds. The AAR will report visitors for the week of Could 24 tomorrow, and it may very properly present the primary outright YoY decline.
What about producers of products and providers within the US? For that we will flip to the regional Fed manufacturing and non-manufacturing indexes. To date in Could All 5 regional manufacturing surveys have been reported, and all however the Texas providers survey. Each kinds of surveys confirmed enhancements from April, by a mean of +2 (for brand new manufacturing orders) and +4 (for providers circumstances) respectively, however the precise circumstances of each confirmed continued contraction, by -6 and -9 respectively. In different phrases, each sectors have been contracting, however at a slower tempo.
I’m additionally unaware of any excessive frequency information on retailer inventories. However Redbook does publish weekly retail gross sales updates, and up to date for the week of Could 24, exhibiting a 6.1% YoY improve:

This continues the development of comparatively robust YoY will increase that started in April. Undoubtedly a few of this was front-running by clients who determined to make anticipated purchases prematurely of tariffs. However by now a few of this improve might be customers’ paying the elevated prices resulting from value hikes.
It’s potential that Redbook’s universe is principally non-durable purchases. I point out this as a result of I had a dialog over the weekend with a neighbor who’s in command of the service division at an area Honda dealership. He reported that after a powerful early April, bookings for repairs fell sharply up to now few weeks, which he attributed to clients being unwilling to incur main bills in view of impending common tariff-related value hikes. If that’s true, it *might* present up in Friday’s private spending report, however since that shall be for April extra possible it is not going to present up but.
Lastly, let me shut with an replace of my “quick and dirty” financial forecasting indicator. This consists of (1) whether or not the inventory market is down YoY; AND (2) whether or not the 4 week common of preliminary jobless claims is increased by 10% or extra YoY. If each of these get hold of for greater than a few weeks, it is rather possible {that a} recession is about to begin. Right here it’s:

No signal of a tariff-palooza! recession is indicated. At the least, not but.
“Real retail sales turn down in April, but continue to reflect consumers’ front-running of tariffs,” Offended Bear by New Deal democrat